
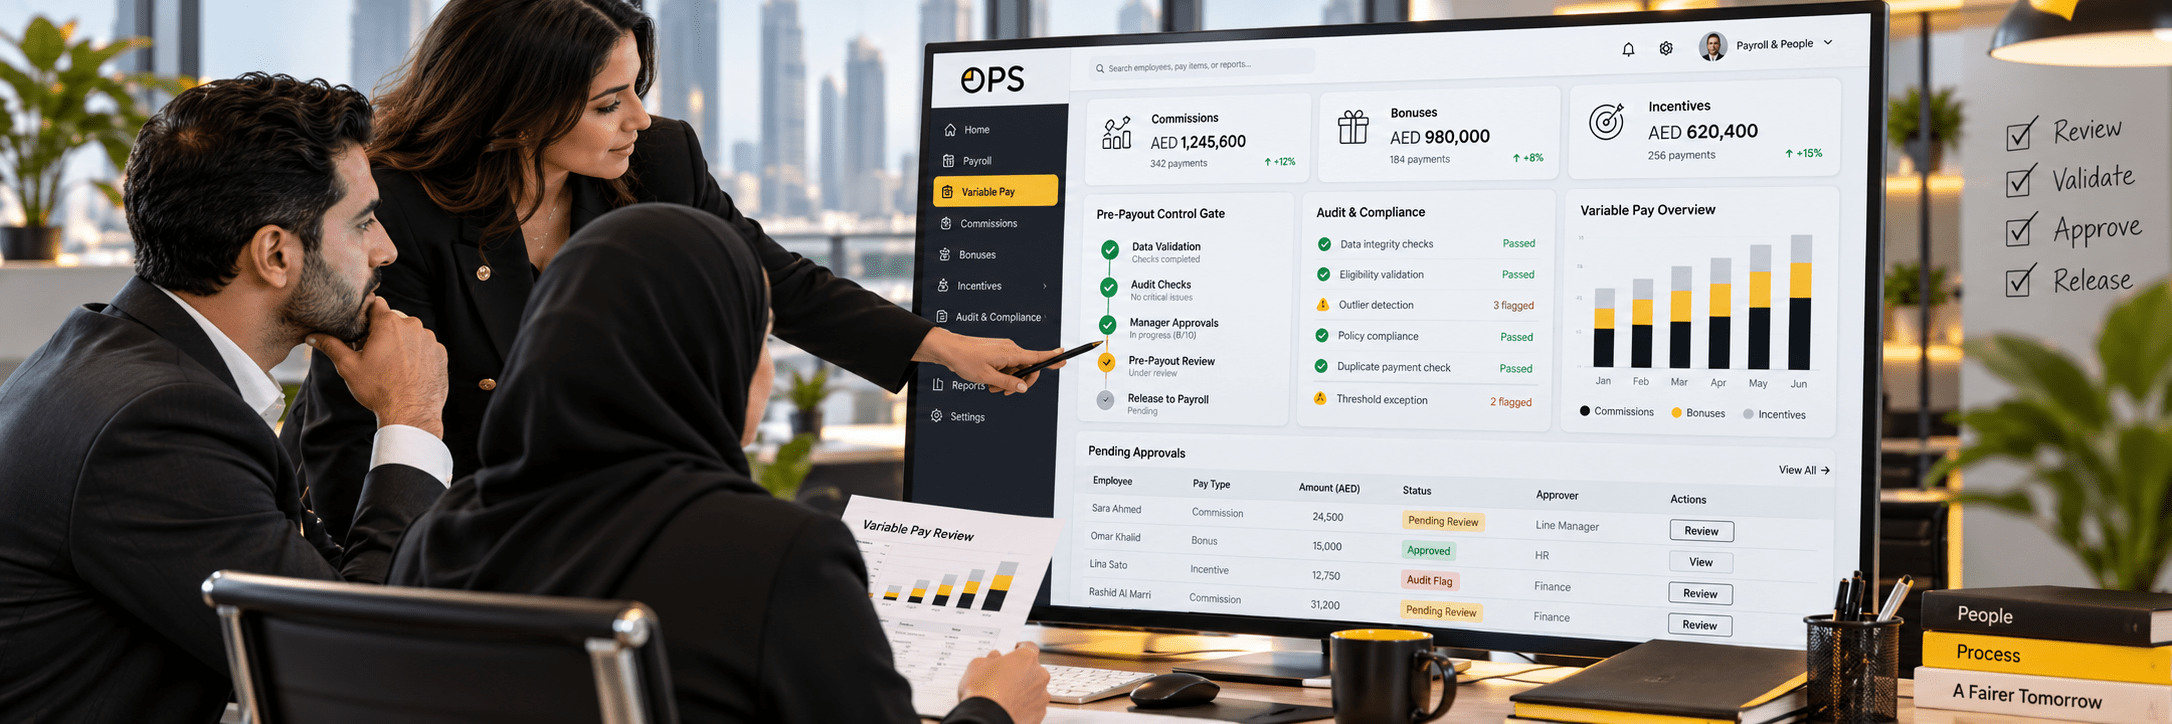
Variable pay payroll audit briefing from OPS — Outsourced Payroll Solutions
|
What is a variable pay payroll audit? Short answer: A variable pay payroll audit checks every commission, bonus or incentive payment against the employment contract, the incentive plan and any clawback conditions before it is disbursed, not after. Unlike fixed salary, variable pay changes every cycle, is calculated outside core payroll logic more often than it should be, and is a common source of undocumented or unauthorised payments in a payroll audit. Across the six GCC states its legal treatment is not uniform: the route for recovering an overpayment, the end-of-service base, the social-insurance position and the wage-reporting treatment all depend on the jurisdiction, the employee category and how the payment is structured contractually. |
Why sales commissions, discretionary bonuses and incentive payments need a pre-payout control gate, not just a payroll calculation across all six GCC states, ahead of Q4 bonus season.
Fixed salary is stable, contractual and calculated the same way every month. Variable pay is none of those things which is why a variable pay payroll audit belongs in the cycle as a control gate, not as a post-mortem after an employee raises a query. This article covers all six GCC states the UAE, Saudi Arabia, Qatar, Bahrain, Kuwait and Oman and sets out where commission and bonus payments break down, what each jurisdiction permits on recovery, how commission interacts with the end-of-service and social-insurance bases, and the pre-payout checks that catch an error while it is still correctable. A group-wide policy can establish common controls, but the statutory treatment has to be configured country by country.
Why variable pay can be a high-risk line in payroll
A commission figure depends on sales data pulled from a CRM or finance system, a discretionary bonus depends on a manager’s judgement, and an incentive payment often depends on a plan document that was updated after the employment contract was signed and never formally reconciled with it.
That combination changing inputs, manual calculation, and a plan document that can drift from the contract is why variable pay tends to generate payroll queries and audit findings out of proportion to its share of total payroll cost. It is also, structurally, the line most likely to be approved quickly under commercial pressure at quarter-end, precisely when scrutiny should be highest. OPS sets out the wider control model in its guide to the sign-off step payroll providers skip.
For employers running payroll in more than one GCC country there is a second problem on top of the operational one. The four questions that decide how a commission is treated how it can be recovered if overpaid, whether it enters the end-of-service base, what social insurance attaches to it, and how it must be reported have different answers in each of the six states, and the answer can turn on the employee’s nationality and category as well as the country. A single group-wide variable-pay policy applied without country configuration will be wrong somewhere.
Where commission and bonus payments break down
Three points of failure appear repeatedly in variable pay, across industries and company sizes.
The contract and the plan disagree
An employment contract may reference commission “as per the applicable incentive plan”, while the plan itself has been revised one or more times since the contract was signed, without a formal amendment or the employee’s acknowledgement. When a dispute arises, the employer is often relying on a plan document that was never contractually binding in the first place.
Clawback provisions exist on paper but are not operationally enforced
Many incentive plans include a clawback provision, for example where a commissioned sale is subsequently cancelled, reversed, or found not to satisfy the conditions of the plan. The existence of a clawback clause does not, on its own, give an employer an unrestricted right to deduct money from future wages and this is where the six GCC states diverge most sharply.
Discretionary bonuses are approved without a documented basis
A discretionary bonus, by definition, is not formula-driven, but that does not mean it should be undocumented. When a bonus is approved verbally or by a single email with no recorded rationale, it is difficult for the employer to demonstrate, if challenged, that the payment was authorised, consistent with policy, and correctly included in or excluded from the relevant statutory calculation base.
Recovering a commission overpayment across the GCC
This is the single most misunderstood point in regional variable-pay administration. Employers frequently assume that because a clawback clause exists, or because the employee agrees in writing, the amount can simply be netted off the next payslip. That assumption does not hold anywhere in the GCC without further checks.
There is no single GCC-wide rule. A clawback clause may establish the contractual basis for a claim, but it does not by itself override the statutory restrictions on deducting from wages. Every one of the six states permits some route to recover money owed to the employer; what differs is whether an overpayment is a named ground, what cap applies, and whether consent or a court order is needed first.
A signed repayment acknowledgement is useful evidence, but it does not replace the statutory requirements governing the deduction. Before recovering anything through payroll, confirm five things: that the debt exists and is evidenced, which recovery route is permitted in that country, the applicable cap, whether the employee’s consent or a court judgment is required first, and whether a different rule applies at final settlement. Several states expressly allow proven employer dues to be set against amounts owed at termination, which is often cleaner than instalment recovery from a live payroll but the mechanism and its conditions vary, and in Bahrain the end-of-service benefit for covered non-Bahraini service is now administered by the Social Insurance Organization rather than paid by the employer, which changes the practical position.
| Country | Governing provision | Position on recovering an overpayment | Limits and conditions |
|---|---|---|---|
| UAE | Article 25, Federal Decree-Law No. 33 of 2021 | Expressly permits recovery of amounts paid to the worker in excess of entitlement. | Capped at 20% of the wage for this ground; where several grounds apply, aggregate deductions must not exceed 50% of the wage. Written consent is not required for this ground, unlike the recovery of a loan. |
| Saudi Arabia | Articles 88, 92 and 93, Labour Law (Royal Decree No. M/51) | Not a listed automatic exception. Article 92 generally requires the worker’s written consent for deductions relating to the employer’s private rights unless another statutory exception applies. | Article 93 generally limits total deductions to half the due wage unless a labour court determines otherwise. On termination, Article 88 permits the employer to deduct a work-related debt from the worker’s entitlements, and requires final dues to be settled within one week where the employer ends the contract, or two weeks where the worker does. |
| Qatar | Article 70, Law No. 14 of 2004 | Substantially more restrictive. Remuneration generally may not be retained or stopped except in execution of a judicial judgment. | Employer loans capped at 10%; judicial attachment at 35%; an overall 50% limit for deductions and debts. A commission overpayment should not be unilaterally netted from salary without confirming a lawful recovery route, and Article 4 voids conditions contrary to the law, so a worker’s waiver does not cure it. |
| Bahrain | Articles 44 and 45, Law No. 36 of 2012 | Article 45 expressly recognises amounts paid to the worker without lawful entitlement among the amounts due to the employer. | Wage attachment or assignment is subject to a 25% limit, rising to 50% for maintenance; employer loans are capped separately at 10% under Article 44. A voluntary assignment of wage requires the worker’s written consent. This is not an unrestricted unilateral clawback right. |
| Kuwait | Article 59, Law No. 6 of 2010 | Permits recovery of debts or loans owed to the employer within the statutory limits. An overpayment must be properly evidenced as such a debt. | 10% for the employer’s own debts or loans; a 25% ceiling across attachment, assignment and deduction for qualifying debts, with maintenance ranking first. Article 62 separately provides that the wage may not be reduced during employment. |
| Oman | Articles 95 and 96, Royal Decree No. 53 of 2023 | Article 96 permits attachment or assignment for qualifying amounts owed to the government or the employer, and requires employer dues to be proven. | Up to one quarter of wages owed, as an aggregate shared with maintenance and government dues. At termination, proven employer dues may also be deducted from the end-of-service gratuity and other entitlements. Recovery of an advance is capped by what the parties agreed under Article 95. |
Variable pay and statutory calculation bases
The six GCC states use different statutory definitions of wage, so an employer operating in more than one should not carry a single payroll calculation base across them. The table below concerns employees who are actually subject to an end-of-service gratuity or indemnity regime, rather than a national pension scheme or another approved arrangement which regime applies turns on nationality and category, and should be established first.
| Country | End-of-service calculation base | Where commission sits |
|---|---|---|
| UAE | Last Basic Wage, under Article 51, for foreign full-time employees subject to that regime | Outside the base. The broader statutory definition of “Wage” may include a percentage of sales or profits, but that does not automatically make commission part of Basic Wage for gratuity. Piece-rate employees are subject to the statutory average-wage calculation, and employees in an applicable alternative savings scheme are treated under that scheme. |
| Saudi Arabia | The last wage is the starting point for the calculation | Commissions, sales percentages and similar variable elements may be included but Article 86 expressly allows the parties to agree that all or some of them are excluded from the end-of-service calculation base. The contract usually decides. |
| Qatar | Last Basic Wage, under Article 54, at a statutory minimum of three weeks for every year of employment | Outside the base. Commission falls within the broader “Remuneration” as defined in Article 1, but not within “Basic Wage”. Piece-rate employees are subject to the applicable averaging rule. |
| Bahrain | Two layers. For covered non-Bahraini service from 1 March 2024, the Social Insurance Organization scheme calculates on basic salary plus social allowance. Service before that date remains an employer liability under Law No. 36 of 2012, where Article 47 applies | Split. SIO states its basis “does not include other allowances and benefits”, so post-commencement benefit does not track commission. Article 47 sets the base as last basic wage plus social allowance, switching to the average wage over the last three months where the worker receives a fixed wage plus commission or a percentage and that averaging still governs the legacy indemnity and, for all private-sector workers, annual-leave-balance compensation under Article 59 and compensation under Articles 99(b) and 111. |
| Kuwait | The last remuneration is generally the basis, under Articles 55 and 62 | Periodic commission can form part of remuneration under the wage provisions. Article 62 contains separate averaging rules three months for piece-rate remuneration, twelve months for cash and in-kind benefits so the treatment depends on how the commission scheme is structured and paid. |
| Oman | Last Basic Wage, under Article 61 of Royal Decree No. 53 of 2023, at not less than one basic wage for every year of service | Outside the base and commission is not named anywhere in the law’s wage definitions. Article 61 operates pending commencement of the Social Protection Law savings arrangements applicable to the worker, so verify the live commencement position before changing an accrual basis. |
Bahrain: the two-layer position employers miss
Bahrain is the most commonly misread of the six, and it changed recently. Since 1 March 2024, under Prime Minister’s Resolution No. 109 of 2023, the Social Insurance Organization administers the end-of-service benefit for covered non-Bahraini private-sector workers, funded by employer contributions of 4.2% of the monthly wage for the first three years of service and 8.4% thereafter. SIO calculates that benefit on the basic salary plus the social allowance, if any, and states that it does not include other allowances and benefits so a commission earner’s post-commencement benefit does not track their commission earnings.
Service before 1 March 2024 remains an employer liability under Law No. 36 of 2012, and there Article 47 applies: the base is the last basic wage plus social allowance, switching to the average wage over the last three months where the worker receives a fixed wage plus commission or a percentage. Article 47 has not been displaced generally it continues to govern that legacy indemnity and, for all private-sector workers, compensation for the annual-leave balance under Article 59 and compensation under Articles 99(b) and 111. Commission therefore stays inside the base for those heads of claim while sitting outside the SIO gratuity base.
One point is worth stating because it circulates in commentary: Resolution 109/2023 does refer to the work-injury contributory wage, which is a broader base but as the fallback applied where an employer misses the data-submission deadline, not as the general rule. Scheme coverage is separately defined by reference to the employment-injury branch, which is a coverage test rather than a wage base. Employers accruing in Bahrain should hold the two periods apart and confirm each employee’s covered status.
Kuwait and Saudi Arabia: structure decides
In Kuwait, periodic commission can form part of remuneration, and Article 62 applies different averaging periods depending on how the pay is characterised twelve months for cash and in-kind benefits, three months for genuine piece-rate work. A commission scheme is not automatically piece-rate, so the classification question should be settled before an accrual basis is chosen rather than after. Saudi Arabia is the mirror image: commission can form part of the last wage, but Article 86 permits the parties to agree to exclude variable elements, which makes the contract the operative document. OPS sets out the country formulas and tenure bands in its guide to GCC end-of-service benefits.
UAE: gratuity on last basic wage
For employees under the UAE’s end-of-service gratuity regime, Article 51 calculates gratuity on the employee’s last basic wage, not on total wage. Because the law draws a Basic Wage / Wage distinction “Basic Wage” being the contract amount excluding allowances and benefits in kind, while “Wage” expressly extends to a percentage of sales or a percentage of profits paid in return for what the worker markets, produces or collects the practical question is not whether “variable pay is excluded” as a blanket rule but how each compensation component is contractually classified. Commission falling within the broader definition of “Wage” does not automatically place it within Basic Wage for gratuity purposes, and a component labelled as commission but structured as part of contractual basic pay will not behave the way the label suggests. Piece-rate employees are subject to the statutory average-wage calculation. Employees enrolled in an applicable alternative end-of-service savings scheme are treated under that scheme’s requirements instead.
Oman: gratuity now, a savings system later
Oman is mid-transition and the timing matters for anyone accruing today. Article 61 of Royal Decree No. 53 of 2023 applies to workers who do not benefit from the Social Protection Law, and applies only until the savings system established under that law comes into force. Royal Decree No. 60 of 2025 deferred that commencement, so expatriate end-of-service in Oman remains employer-paid gratuity on final basic wage for the present. Employers should confirm the current commencement date before changing an accrual basis, and note that Article 61 permits pre-scheme service to be settled either into the savings system or to the worker, calculated at the basic wage on the date of settlement.
Social insurance: check nationality, branch and wage definition
Variable pay should not be assessed against a single GCC-wide social-insurance rule. The treatment depends on the employee’s nationality, which insurance branch applies, and the statutory definition of contributory wage in that country. The mistake to avoid is assuming that an expatriate employee sits outside social insurance altogether because they sit outside the pension branch.
Saudi Arabia is the clearest case, and the one that bears most directly on variable pay. GOSI states that commission, the percentage of the sales value and the percentage of the profit are considered basic wage for contributory-wage purposes, whether paid alone or in addition to a fixed wage. The contributory wage is the basic wage plus the housing allowance, subject to a maximum of SAR 45,000 a month. Coverage then differs by branch: the occupational-hazards branch compulsorily covers all Saudi and non-Saudi workers, at 2% of contributory wages payable by the employer, while the annuities branch compulsorily covers Saudi workers. So commission does carry an employer contribution cost for an expatriate in Saudi Arabia, through the occupational-hazards branch. Because the framework differs between employees registered before and after the Social Insurance Law under Royal Decree No. M/273 took effect on 3 July 2024, confirm the applicable regime and category before calculating. GCC nationals working in Saudi Arabia are insured in their home state’s scheme under the GCC extension of insurance protection rather than in GOSI’s annuities branch.
Bahrain’s non-Bahraini end-of-service contribution regime is a separate matter, set out above: from 1 March 2024 the Social Insurance Organization administers the benefit and the basis is basic salary plus social allowance. Bahraini nationals are covered by the pension branch; expatriates are covered for employment injury and unemployment rather than pension.
Oman shows why the pension branch is the wrong test. Under the Social Protection Law, Royal Decree No. 52 of 2023, non-Omani workers sit outside the pension and job-security branches but they are already inside employer-funded leave branches: maternity leave from 19 July 2024 and sick and extraordinary leave from 19 July 2026, each at 1% payable by the employer. Insurance against work injuries and occupational diseases, and the provident scheme for expatriate end-of-service, are provided for but not yet in force for non-Omanis; both were deferred by Royal Decree No. 60 of 2025 and are currently scheduled rather than fixed, so confirm the live position with the Social Protection Fund. Note also that the law defines the contribution wage only as the wage not exceeding the ceiling for each branch, without specifying which pay components it comprises so whether commission enters that base should be confirmed with the Fund rather than assumed.
In Qatar and Kuwait the retirement and social-insurance schemes cover nationals the GRSIA in Qatar, PIFSS in Kuwait with expatriate workers receiving end-of-service entitlements instead. For national and GCC-national employees in any of the six states, the contributory-wage treatment of commission should be checked against the applicable authority and the contribution-wage definition that applies to that employee, since those definitions do not all name commission.
The compliance angle: variable pay, wage protection and audit trails
Every GCC state now operates some form of wage protection or salary-reporting regime, and each treats variable pay slightly differently in the file. The common principle is the one worth holding on to: where commission forms part of contractual remuneration, it should move through the same evidenced channel as fixed salary rather than through an undocumented parallel process. Paying it by separate manual transfer or in cash leaves part of the wage unevidenced, which bears on the employer’s wage-protection position in its own right, separately from whether the amount was calculated correctly.
The control principle is therefore not that every GCC jurisdiction uses the same commission field it is that payroll must be able to reconcile four things: the contractual entitlement, the approved calculation, the amount actually paid, and the wage-protection or salary-reporting record applicable to that entity. Bahrain is the one state where commission has its own named reporting category, so a variable payment made outside the file reads as an omission rather than merely as undocumented. Elsewhere, where a country’s published specification does not address a component, confirm it with the authority or the approved provider rather than reasoning across from another GCC state.
Wage-payment deadlines and filing windows differ again across the six states, and several changed during 2025 and 2026. Those are set out separately in OPS’s guide to GCC payroll deadlines 2026, and the mechanics of each system in its overview of GCC wage protection systems. For UAE employers, the pre-filing controls are in the WPS pre-submission checklist.
| Country | System and authority | How commission is treated in the file |
|---|---|---|
| UAE | WPS, via MOHRE-registered banks and exchange houses. Ministerial Resolution No. 340 of 2026, effective 1 June 2026 | Contractual commission of the percentage-of-sales kind falls within the statutory definition of “Wage”, so it belongs in the evidenced wage payment rather than alongside it |
| Saudi Arabia | Wage Protection Program; wage and reconciliation data submitted through the Mudad system, under the MHRSD | Contractual wages and the variable-pay components forming part of them should be reconciled with payroll records and the wage file |
| Qatar | WPS with a Salary Information File, under the Ministry of Labour with the Qatar Central Bank. Law No. 1 of 2015 amending Article 66, and Ministerial Decision No. 4 of 2015 | Article 66 requires salaries and other sums due under the employment contract to be transferred to the employee’s account at a financial institution in Qatar, so contractual commission is in scope. Confirm the current file specification with the Ministry before assuming how a component is reported |
| Bahrain | Enhanced Wage Protection System, administered by the LMRA with the Central Bank of Bahrain | The most explicit of the six. The LMRA guideline separates fixed wage, variable wage and social allowance, and lists commissions based on sales or performance as variable wage. A monthly file is required even where nothing has changed |
| Kuwait | Payment into local financial-institution accounts with statements reported to the authority, under Articles 56 and 57, administered by PAM | Published guidance does not set out element-level treatment for variable pay. Reporting is built around the salary registered for the worker; confirm the current requirements with PAM |
| Oman | WPS via institutions regulated by the Central Bank of Oman, under the Ministry of Labour. Ministerial Decision No. 729 of 2024 | No published field specification for variable components. The transfer must accord with the employment contract, and contracts must be updated when wages change |
UAE free zones, DIFC and ADGM
Within the UAE, free-zone treatment must be checked against the employing entity’s own licensing authority, because there is no single rule that safely covers every free zone. Some sit within UAEWPS: JAFZA, for example, requires all businesses registered with the zone to comply with it. The financial free zones are different again ADGM operates under its own employment regulations and does not prescribe payment through UAE WPS, requiring instead that wages be paid into a bank account in the employee’s name within defined periods, while DIFC employment relationships are governed by DIFC’s separate Employment Law. Confirm the rule that applies to the specific authority rather than assuming every UAE entity follows the same process. OPS maps the divergences in free zone vs mainland payroll in the UAE.
Common variable-pay control failures
| Common failure | Operational risk | Control |
|---|---|---|
| Commission plan not reconciled with the employment contract | Payment disputed or unenforceable if challenged by the employee | Formal plan versioning, with employee acknowledgement on every material change |
| Clawback clause exists but is not tracked operationally | Employer cannot recover commission on a cancelled or defaulted sale | A defined clawback-tracking step applied to the next calculation before it is approved with the permitted recovery route, the applicable cap and any consent or judgment requirement confirmed for that country before any deduction is made |
| A single group-wide variable-pay policy applied across GCC entities | End-of-service accruals and recovery practices that are lawful and correctly sized in one GCC state but not in another | Country-specific rules held per entity for the recovery route, the end-of-service base and the wage-reporting treatment, keyed to each employee’s applicable regime |
| Discretionary bonus approved without a documented basis | No audit trail to demonstrate consistent, authorised decision-making | A recorded approval, with rationale, before the bonus enters the payroll file |
| Contractual commission paid outside the applicable wage-protection process | Part of the wage is left unevidenced in the wage file, affecting the establishment’s wage-protection position | All variable pay forming part of contractual wage routed through the process that applies to the entity’s jurisdiction and licensing authority |
| Sales data pulled manually from CRM into a payroll spreadsheet | Transcription error inflates or understates commission before it is paid | A single verified data source, checked by someone other than the preparer, before disbursement |
| Variance checks run on aggregate totals only, not per employee | A single anomalous payout stays hidden inside a wide aggregate band and reaches the bank file | A per-employee variance test against that employee’s own history, plus a threshold hold requiring client confirmation on large individual payouts |
A maker-checker gate before payment is released
A maker-checker process is a payroll governance control rather than a general statutory requirement under GCC labour law which is precisely why it is so unevenly applied to variable pay. Under it, the person who prepares a commission, bonus or incentive calculation is not the sole person authorising the payment, and that approval is recorded before the figure enters the payroll file, not after. Most organisations already do this for fixed payroll. Variable pay is treated far more loosely, because it is often handled as a sales or line-manager decision rather than a payroll one.
What the second reviewer should verify
A practical pre-payout gate has a second reviewer verify, for every commission, bonus or incentive line:
- That the amount traces to a verified source.
- That it is consistent with the current, acknowledged incentive-plan version and the contractual entitlement.
- That prior-period adjustments and clawback conditions have been applied.
- That individual variances against that employee’s own history are explained.
- That the payment is treated correctly for the payroll, end-of-service and wage-protection requirements of the country the entity sits in not the group’s home country.
For higher-value or unusual payments, an additional approval threshold adds protection against scheme misassignment, bad source data and exceptional individual payouts.
|
OPS expert view Variable pay disputes rarely start as a disagreement about the number. They start as a disagreement about which version of the plan applied, or whether an approval actually happened. The commercial fix and the compliance fix are the same control: a documented, checked approval before the payment is made, not a reconciliation exercise after an employee raises a query. The regional pattern reinforces it in most of the GCC, recovering an overpayment from a live payroll needs a lawful route, a cap check and often the employee’s written consent or a court order, none of which is quick. The pre-payout gate is the control that avoids needing any of them. |
Case study: a commission scheme misassignment, caught in a single cycle
A KSA-based B2B sales organisation runs commission payouts alongside monthly salary. In one cycle, two employees were assigned to the wrong commission scheme, producing a combined overpayment exposure of SAR 12,000,000. The misassignment was identified during the pre-payout review and corrected within the same cycle. Net financial impact: none.
|
Why the aggregate check did not flag it The monthly review compared each scheme’s aggregate commission total against its normal operating band of SAR 800,000 to 8,000,000. That band is roughly ten times as wide at the ceiling as at the floor, so an individual payout can be several million riyals out of line and still leave the aggregate it sits in comfortably inside range. Both inflated payouts were absorbed that way. Each figure was plainly anomalous against that employee’s own payout history; neither was anomalous against the total it was being measured in. |
Root cause: the variance check operated at scheme-aggregate level only. There was no per-employee variance test against prior-period history, and no threshold-based hold requiring client confirmation before an unusually large individual payout entered the payroll file. The control was correctly designed for the risk of a scheme-wide calculation error and blind to the risk of a scheme misassignment affecting individual employees.
What changed as a result
Both controls are now standard in the cycle. Every commission line is variance-tested against that employee’s own payout history as well as against the scheme aggregate, and any individual payout above a defined threshold is held for explicit client confirmation regardless of how the aggregate total reads. Nothing is released until the client signs off.
The case also shows why the timing of the control matters more than its existence, and why that is even truer outside the UAE. Caught before release, an error of this kind is a reconciliation exercise inside the cycle. Caught afterwards, it becomes a recovery conversation at exactly the point an employer most needs the employee’s trust in the process and in Saudi Arabia, where this incident occurred, an overpayment is not a listed automatic deduction exception. Recovery from a live payroll would generally require the worker’s written consent under Article 92 and sit within the Article 93 limit, while Article 88 allows a work-related debt to be deducted from entitlements on termination. None of those routes is as clean, as quick, or as certain as correcting the figure before it is released.
What OPS manages for clients
For payroll audit and variable-compensation clients, OPS reconciles incentive-plan terms against employment contracts, applies documented maker-checker approval before any commission or bonus enters the payroll file, variance-tests every line at both employee and scheme level, tracks clawback conditions across cycles rather than treating each payout as a standalone event, and validates that variable pay is reported through the same compliant salary channel and audit trail as fixed salary. Each client entity is configured to its own country rules, so the recovery ground, the end-of-service base and the wage-file treatment are held per entity rather than assumed from the group’s home jurisdiction. This sits inside OPS’s managed payroll service, and the wider provider comparison is set out in payroll outsourcing in the UAE. Nothing is released until the client signs off.
Pre-payout variable pay payroll audit checklist
- Every active incentive plan is reconciled against the employment contract it relates to, with the current version identified.
- Where an incentive-plan amendment affects contractual remuneration, or where the contract, plan terms or applicable local law require consent or acknowledgement, the employee’s acceptance is documented before the revised terms are applied.
- Commission figures trace back to a single, verified data source, not a manually re-entered spreadsheet.
- Every individual payout is variance-tested against that employee’s own history, not only against the scheme or team aggregate.
- Clawback conditions from prior periods have been checked before the current payment is calculated, with the permitted recovery route, the applicable cap and any consent or judgment requirement for that specific country confirmed before any deduction.
- Discretionary bonuses carry a recorded approval and rationale before entering the payroll file.
- The person approving the payment is not the person who calculated it.
- Any individual payout above a defined threshold is held for explicit client confirmation before it enters the payroll file.
- All variable pay forming part of contractual wage is scheduled through the wage-payment and reporting process that applies to the employing entity’s jurisdiction and licensing authority, and reconciles to the entitlement, the approved calculation and the amount paid.
- For multi-country groups, the end-of-service accrual basis reflects each country’s own rule and each employee’s applicable regime — including, in Bahrain, the split between SIO-administered service from 1 March 2024 and earlier service under Law No. 36 of 2012.
Frequently Asked Questions
What is variable pay governance?
It is the set of controls contract reconciliation, documented approval, clawback tracking and compliant disbursement applied to commissions, bonuses and incentive payments before they are paid, rather than reviewed only if a dispute arises afterwards.
Can an employer recover a commission overpayment from an employee’s wages in the GCC?
There is no single GCC-wide rule, and a clawback clause does not by itself override the statutory limits on deducting from wages. The UAE is the most permissive: Article 25 of Federal Decree-Law No. 33 of 2021 expressly permits recovery of amounts paid in excess of entitlement, capped at 20% of the wage with a 50% aggregate limit, and does not require written consent for that ground. Bahrain’s Article 45 of Law No. 36 of 2012 expressly recognises amounts paid to the worker without lawful entitlement among the amounts due to the employer, subject to a 25% limit. In Saudi Arabia an overpayment is not a listed automatic exception Article 92 generally requires the worker’s written consent for deductions relating to the employer’s private rights, Article 93 limits total deductions to half the due wage unless a labour court determines otherwise, and Article 88 permits a work-related debt to be deducted from the worker’s entitlements on termination. Kuwait and Oman allow recovery of debts owed to the employer within caps of 25% and one quarter of wages respectively, with Oman requiring the dues to be proven. Qatar is the most restrictive: remuneration generally may not be retained or stopped except in execution of a judicial judgment. Before recovering anything through payroll, confirm the debt and its evidence, the permitted recovery route, the applicable cap, and whether consent or a judgment is required first.
Which GCC countries include commission in the end-of-service calculation?
It depends on the country and on the employee’s applicable regime, so establish which regime governs before choosing an accrual basis. Saudi Arabia can include commissions and sales percentages in the last wage, but Article 86 allows the parties to agree to exclude all or some variable elements. Kuwait treats periodic commission as capable of forming part of remuneration, with Article 62 averaging cash and in-kind benefits over the last twelve months and piece-rate earnings over the last three. Bahrain has two layers: for covered non-Bahraini service from 1 March 2024 the Social Insurance Organization scheme calculates on basic salary plus social allowance and does not include other allowances and benefits, while earlier service remains an employer liability under Law No. 36 of 2012, where Article 47 switches the base to the average wage over the last three months for a worker receiving a fixed wage plus commission or a percentage. That Article 47 averaging also continues to govern annual-leave-balance compensation under Article 59 and compensation under Articles 99(b) and 111 for all private-sector workers. The UAE, Qatar and Oman fix the base at basic wage, which leaves commission outside it and in the UAE, commission falling within the broader definition of “Wage” does not automatically make it part of Basic Wage for gratuity purposes.
Should commission be paid through the same channel as salary?
Where commission forms part of remuneration due to an employee, it should be processed and evidenced in accordance with the wage-payment and reporting rules that apply to the employing entity. The technical treatment is not identical across the GCC. Bahrain is the most explicit: its Enhanced Wage Protection System separates fixed wage, variable wage and social allowance in the salary file, and lists commissions based on sales or performance as variable wage. Qatar’s amended Article 66 requires salaries and other sums due under the employment contract to be transferred to the employee’s account at a financial institution in Qatar, so contractual commission is in scope. UAE establishments subject to MOHRE’s WPS operate under the framework updated by Ministerial Resolution No. 340 of 2026, effective 1 June 2026, and free-zone treatment is authority-specific JAFZA entities use UAEWPS, while ADGM and DIFC operate under their own regimes. Where a country’s published specification does not address how a particular component is reported, confirm it with the authority or the approved provider rather than reasoning across from another GCC state.
Does variable pay attract social insurance contributions in the GCC?
Not against a single GCC-wide rule it depends on the employee’s nationality, which insurance branch applies, and the contributory-wage definition in that country. Saudi Arabia is the clearest case: GOSI states that commission, the percentage of the sales value and the percentage of the profit are considered basic wage for contributory-wage purposes, with the contributory wage subject to a maximum of SAR 45,000 a month, and its occupational-hazards branch compulsorily covers all Saudi and non-Saudi workers at 2% of contributory wages payable by the employer. So commission does carry an employer contribution cost for an expatriate in Saudi Arabia, even though the annuities branch compulsorily covers Saudi workers. Do not assume an expatriate sits outside social insurance altogether because they sit outside a pension branch: in Oman, non-Omani workers are already inside employer-funded maternity-leave insurance from 19 July 2024 and sick and extraordinary leave insurance from 19 July 2026, each at 1%, while work-injury cover and the expatriate provident scheme were deferred by Royal Decree No. 60 of 2025 and remain scheduled rather than in force. In Bahrain, expatriates are covered for employment injury and unemployment, with end-of-service administered by the Social Insurance Organization since 1 March 2024. In Qatar and Kuwait the retirement schemes cover nationals. Where a national or GCC-national employee earns commission, confirm the contributory-wage treatment with the relevant authority.
What happens if an incentive plan is updated but the employment contract is not?
An updated incentive plan is not automatically invalid simply because the employment contract has not been rewritten. The position depends on how the plan is incorporated into the employment relationship, whether the employer retained a contractual right to amend it, whether the change affects an existing contractual entitlement, and the requirements of the applicable jurisdiction. Material changes affecting contractual remuneration should be documented carefully and, where required, formally accepted or acknowledged by the employee. In Saudi Arabia, bonuses and similar payments can in some circumstances become part of actual wage through the employment contract, work regulations or established practice. Several GCC labour laws also void conditions that reduce a worker’s statutory entitlements, so a plan amendment cannot be used to cut below the statutory floor. Employee acknowledgement of every plan revision is a sound control, but it is not a universal statutory GCC requirement treat it as required where the change affects contractual remuneration or where the contract, plan terms or local law require acceptance.
Is a maker-checker control necessary for small variable-pay teams?
A maker-checker control is not generally a statutory labour-law requirement anywhere in the GCC, but it is a strongly recommended payroll governance practice and the regional recovery position makes it more valuable, not less, since recovering an overpayment from a live payroll in most of the GCC requires a lawful route, a cap check and often the employee’s written consent or a court judgment, none of which is quick. Even in a small organisation, calculation and approval can usually be separated, or an independent reviewer appointed for unusually large or higher-risk variable-pay payments. Team size affects how the control is resourced, not whether it is worth having.
Book a pre-payout commission review with OPSAhead of Q4 bonus and commission season, OPS can review how your variable pay is reconciled, approved and evidenced before it reaches the payroll file per entity, per country. You can also book a payroll consultation or visit www.ops.ae. |
Scope and basis: this article covers private-sector payroll considerations across the UAE, Saudi Arabia, Qatar, Bahrain, Kuwait and Oman. Legal treatment can vary by employee nationality, employing entity, free-zone or special-jurisdiction status, contractual structure and applicable social-insurance regime. Statutory positions have been reviewed against current legislation and official authority guidance available at the date of review. Wage-protection system specifications and social-insurance implementation dates can change, and operational field treatment should be confirmed against the latest authority or approved-provider guidance before payroll processing. This article provides general payroll-compliance information and does not constitute legal advice.
Sources
- UAE — Ministry of Human Resources and Emiratisation (MOHRE); Ministerial Resolution No. 340 of 2026 (Wage Protection System), effective 1 June 2026; Federal Decree-Law No. 33 of 2021 — Article 25 (wage deductions), Article 51 (end-of-service gratuity) and the Wage / Basic Wage definitions
- Saudi Arabia — Saudi Labour Law, Royal Decree No. M/51, Articles 86, 88, 91, 92 and 93; GOSI employer guidance on contributory wage and branch coverage; MHRSD on cases of deduction from wages; GOSI contributory-wage guidance; Royal Decree No. M/273 (Social Insurance Law), effective 3 July 2024; Mudad
- Qatar — Law No. 14 of 2004 (Labour Law) on the Al Meezan legal portal — Articles 1, 4, 54, 70 and 71; Law No. 1 of 2015 amending Articles 66 and 145, and Ministerial Decision No. 4 of 2015 (Wage Protection System); Ministry of Labour; GRSIA
- Bahrain — Law No. 36 of 2012, Labour Law for the Private Sector — Articles 1, 44, 45, 47, 59, 99, 111 and 116; LMRA Wage Protection Guideline; Legislative Decree No. 21 of 2020 and Prime Minister’s Resolution No. 109 of 2023, in force 1 March 2024 — SIO on end-of-service gratuity for non-Bahrainis and SIO on end-of-service benefits
- Kuwait — Law No. 6 of 2010 on Labour in the Private Sector — Articles 51, 53, 55, 56, 57, 59 and 62; Public Authority for Manpower (PAM) and its AS’HAL portal; PIFSS
- Oman — Labour Law, Royal Decree No. 53 of 2023 — Articles 1, 61, 90, 95 and 96; Social Protection Law, Royal Decree No. 52 of 2023, as amended by Royal Decree No. 60 of 2025; Ministerial Decision No. 729 of 2024 (Wage Protection System); Social Protection Fund on coverage of non-Omani workers
- UAE free zones — JAFZA — Wage Protection System for Jafza companies; ADGM Employment Affairs Office — Guidance on the ADGM Employment Regulations 2024; DIFC Employment Law — difc.ae