
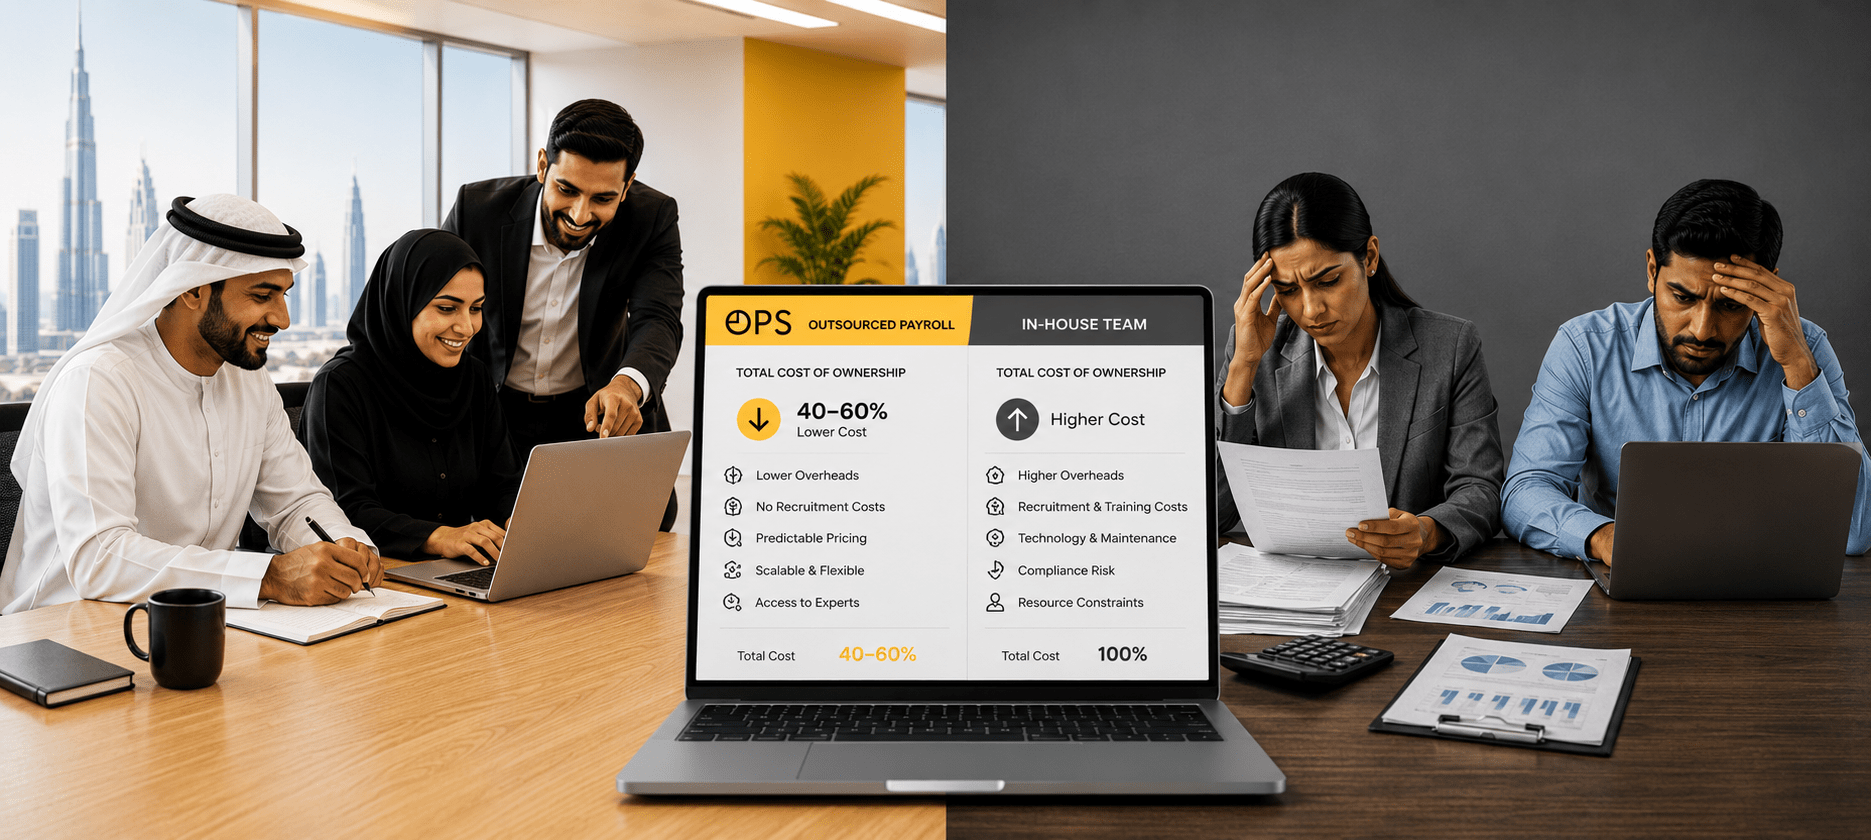
What does payroll outsourcing cost in the UAE, and how does it compare with an in-house team? Short answer: The payroll outsourcing cost UAE question only makes sense against a full in-house figure, and most in-house figures are too low because they price the payroll salary and little else. A real total cost of ownership adds systems, statutory registrations per UAE entity, regulatory reconfiguration, record retention, cover for absence, and the cost of correcting errors after they reach a bank file. A comparison only means something when every one of those lines is priced on both sides. This guide gives the cost lines, the calculation method, and the UAE statutory load behind them. |
Most in-house payroll budgets in the UAE price one thing accurately: the salary of the person who runs payroll. Everything else is either absorbed into other departments’ time or discovered later. That is why the two models rarely get compared on the same basis, and why payroll outsourcing cost in the UAE is usually set against an in-house figure that is too low to be the real one.
The fix is not a better estimate. It is a longer list of cost lines, applied identically to both sides. Statutory contribution rates are not on that list, because they are the same cost whichever model you choose. What differs between the two models is the work of applying them, per entity, every cycle, and re-applying them each time a rule moves. For the qualitative side of this decision, OPS covers it separately in payroll outsourcing versus in-house payroll.
Why an In-House Payroll Cost Is Usually Understated
An in-house payroll function carries four kinds of cost, and only the first is normally visible in a budget line.
People. The payroll role itself, the employer cost attached to that role, and the finance and HR hours spent preparing inputs, checking outputs and approving the run.
Systems. Licences, per-employee fees, entity configuration, bank and wage-protection file interfaces, payslip distribution and employee access.
Statutory administration. Registration and maintenance on each authority portal, per legal entity. Filing time per cycle. Record retention. Evidence for inspections and audits.
Risk and contingency. Correcting errors, off-cycle reruns, exposure to late filing, response time when an authority asks a question, and cover when the one person who knows the payroll is unavailable.
The third and fourth categories are where the two models genuinely diverge. They are also the two that in-house models book at zero.
Payroll Outsourcing Cost UAE: The Total Cost of Ownership Register
Use the table below as the cost register for both models. Price every row twice, once for an in-house function and once for the outsourced scope actually quoted to you. The second column is the calculation method, so the figures come from your own payroll rather than from a benchmark that does not describe your entities.
The third column is the honest part. It marks the rows that in-house budgets in this region routinely leave out.
| Cost line | How to work it out | Usually counted in-house? |
|---|---|---|
| Payroll role, total employer cost | Basic salary plus allowances, plus end-of-service accrual, plus insurance and visa cost. Not the basic salary alone. | Partly. The salary is counted, the accrual and visa cost often are not. |
| Finance and HR input time | Hours per cycle spent gathering inputs, reviewing variances and approving, times the loaded hourly cost of the people doing it, times 12. | No. It sits inside other departments’ budgets. |
| Cover for the payroll role | Either the cost of a trained second person, or the cost of the cycle running late. Pick one and price it. There is no zero option. | No. |
| Turnover and rehire | Recruitment cost plus the handover period, divided across the expected tenure of the role. | No. |
| Payroll and HR system | Annual licence plus per-employee fees, at your actual headcount, including leavers processed mid-year. | Yes. |
| Country and entity configuration | One-off implementation cost per legal entity, amortised over the life of the system, plus each new entity added since. | Only in year one. |
| Bank and wage-protection file interface | Build and test cost per bank and per file format, plus retesting whenever a format or a portal changes. | Rarely. |
| Statutory compliance touchpoints maintained | List the payroll systems, authorities and filing or payment channels per UAE entity from the table in the next section, then estimate hours per cycle against each. | No. |
| Regulatory change reconfiguration | Count the rule changes that touched your payroll in the last 18 months, and price each as a configuration project, not as a monthly task. | Almost never. |
| Record retention and audit evidence | Storage and indexing cost across the longest retention period that binds you, not the shortest. In the UAE those two periods are different. | No. |
| Error correction and off-cycle runs | Number of corrections and out-of-cycle payments last year, times the hours each consumed across payroll, finance and HR. | No. |
| Late-filing and enforcement exposure | Not a fine estimate. Price the consequence that actually bites: suspension of labour-authority services, which in several states blocks work permits. | No. |
| Inspection and audit response | Hours spent reconstructing evidence for the last audit or authority query. If none has happened yet, use the hours it would take today. | No. |
| Provider fee, at agreed scope | The quoted fee, plus anything the quote lists as outside standard scope that you know you will use. Ask for inclusions and exclusions in writing. | This is the outsourced side of the register. |
Two rows carry most of the difference between the models, and both are in the statutory category rather than the people category. They are worth taking separately.
The UAE Statutory Load Is Several Obligations, Not One
An employer running payroll in the UAE does not maintain one compliance obligation. It maintains a set of registrations across several authorities, each on its own cadence, with its own calculation base and its own filing channel.
Read the block below as the payroll compliance systems, authorities and filing or payment touchpoints a UAE payroll team keeps current, per legal entity. These are not a like-for-like numeric count.
| Key payroll compliance systems, authorities and filing/payment touchpoints | MOHRE establishment file and permits; the Wage Protection System through an authorised bank or exchange house; GPSSA via Ma’ashi, where UAE or GCC nationals are employed; the Nafis platform where Emiratisation obligations apply above the relevant headcount threshold; the unemployment insurance subscription, which is the employee’s own obligation but is usually deducted and tracked through payroll; and Federal Tax Authority corporate tax registration. |
| Wage-payment window | Wages fall due on the first day of each Gregorian month under Ministerial Resolution No. 340 of 2026, effective 1 June 2026. The previous 15-day grace period no longer applies. Payment runs through the Wage Protection System or another Ministry-approved system. |
| End-of-service calculation base | For eligible foreign full-time workers completing at least one year of continuous service, calculated on last basic wage: 21 days’ basic wage per year for the first five years and 30 days’ basic wage per year after, with pro-rata entitlement for fractions of a year. Cap expressed as two years’ total wage. |
| Payroll record retention | Two separate duties. Not less than two years from the end of service under the labour law, and at least seven years after the end of the tax period for records supporting a tax filing. |
What these compliance touchpoints cost an in-house team
The list looks manageable. In practice a UAE payroll team keeps several of these current at once: the MOHRE establishment file and permits, the Wage Protection System through an authorised bank, GPSSA where UAE or GCC nationals are employed, the Nafis platform where Emiratisation thresholds apply, the employee unemployment insurance subscription, and Federal Tax Authority registration. Each has its own portal, its own cadence and its own evidence trail, and a group with more than one UAE legal entity maintains the full set again for each entity.
That matters for cost because the obligations do not line up on one date. Wages are due on the first of the month, while the WPS file, GPSSA and Federal Tax Authority duties fall on their own cycles, so the work cannot be batched into a single week. In-house payroll cost per entity rises faster than headcount when a second and third UAE entity is added, because the whole set is maintained again for each.
The end-of-service calculation base is a common in-house error
The end-of-service base is the single most expensive thing to get wrong, and the reason gratuity is a recurring source of in-house error. In the UAE, gratuity accrues on last basic wage, but the two-year cap is expressed on total wage, which is a genuine trap for anyone building a single formula from the wrong denominator.
The UAE accrues end-of-service on last basic wage: 21 days’ basic wage for each of the first five years and 30 days’ basic wage for each subsequent year, with the two-year cap expressed on total wage. UAE nationals and expatriates sit on different statutory tracks, nationals through GPSSA and the pension system and expatriates on the gratuity route, and GCC nationals working in the UAE are insured through their home-state scheme via the GPSSA extension system rather than the UAE scheme. The UAE does not reduce end-of-service for resignation in the way some other jurisdictions do, so an award should be costed on the UAE rule rather than a formula carried over from elsewhere. There is more detail on the mechanics in the OPS guide to GCC end-of-service benefits.
The Three Cost Lines Finance Teams Miss Most Often
1. Regulatory change is a project cost, not a monthly one
In-house models price payroll as a repeating monthly task. Regulatory change does not behave that way. It arrives as a discrete reconfiguration project with a deadline set by someone else.
Recent examples make the point without any modelling. The UAE moved the wage-due date to the first of each Gregorian month under Ministerial Resolution No. 340 of 2026, removing the former 15-day grace concept, and changed the Nafis pension support arrangement for enrolled Emirati employees, covered separately in the OPS note on Nafis pension changes 2026. Each arrived as a dated reconfiguration with a deadline set elsewhere, not as a monthly task. The dates behind the wage-payment window sit in the OPS GCC payroll deadlines guide.
Count how many of those touched your entities, then price each as configuration, testing and a parallel check before the affected cycle. In-house budgets almost always record that number as zero.
2. Cover is a cost whether you buy it or not
A one-person payroll function has a single point of failure with a hard monthly deadline. The cost of cover is either the salary of a trained second person, or the cost of a late cycle. There is no third option, and pricing it at nothing is a common error in an in-house comparison.
3. Retention runs longer than the labour law says
In the UAE two separate duties run in parallel. The labour law requires worker records for not less than two years from the end of service. Where payroll records form part of the records supporting a tax filing, Federal Tax Authority requirements apply to those records for at least seven years after the end of the tax period. Neither duty displaces the other, and retention design should be set with tax and legal advisers, and against applicable data protection limits.
An archive built only to the shortest applicable period may not satisfy the longer one. Building and indexing it to the longest period that binds you is a real, ongoing cost that belongs in the register.
How to Run the Comparison for Your Own Organisation
Six steps, in this order.
- List your UAE legal entities. Treat each entity as a separate entry, since the full set of registrations is maintained again for each.
- List the statutory compliance touchpoints from the table above for each entity. Multiplied across entities, that is the administrative surface an in-house team maintains.
- Price every row of the cost register for the in-house model, using your own hours and your own salaries. Do not skip a row because it is hard to estimate. Put a number on it and mark it as an estimate.
- Price the same register against a written outsourced scope. Ask for inclusions, exclusions and chargeables in writing, because the rows that are outside standard scope are the ones that turn a quote into an invoice you did not expect.
- Add the rows that are usually left out entirely: cover for absence, regulatory reconfiguration over the last 18 months, and record retention priced to the longest applicable period.
- Compare like for like over three years, not one. A first-year comparison flatters whichever model you are already running, because implementation is sunk on one side and visible on the other.
OPS expert view The cost line that decides these comparisons is not running payroll. It is maintaining the payroll calendar. Running a cycle is the affordable, repeatable part, and an in-house team with a decent system does it competently. What in-house models do not fund is the work of keeping the UAE payroll calendar current when the rule underneath it moves, because that work has no monthly slot to sit in. In practice the in-house cost is not a flat monthly figure. It spikes at three moments: the cycle after a rule changes, the cycle when the person who knows the payroll is away, and the month a senior employee leaves and the end-of-service base has to be resolved against the right definition. A total cost of ownership model built on an average month prices none of those three, and they are where the money actually goes. |
What OPS Manages in This Model
OPS is a managed payroll and HR operations provider for the Middle East, running payroll as a controlled monthly cycle rather than a monthly output. That discipline is what OPS means by payroll assurance. Against the cost register above, this is what OPS takes on.
OPS builds and maintains the payroll calendar per entity, and configures each entity to its own approval flow and statutory rules. OPS applies regulatory change to that calendar before the affected cycle, so a rule change becomes a configuration OPS has already made rather than a project the client has to fund. OPS runs validation, quality assurance and variance review before anything reaches a bank file, and prepares the standard bank and wage protection files. Statutory filings and wage protection submissions are handled inside the run rather than added afterwards. Reporting and approval evidence is produced each cycle, which is what audit readiness means in practice. HR administration, leave, employee records and employee self-service through gulfHR, OPS’s connected platform within Gulf Solutions Group, sit alongside payroll under the same accountable provider.
Two structural points matter for the cost comparison. Each client has a named specialist with a named backup owning the account end to end, which is the cover line priced rather than assumed. And nothing is released until the client signs off, so the review gate the register calls for exists as a step in the cycle.
If you are comparing providers rather than models, the OPS guide to telling a governed provider from a payroll processor sets out what to ask, and the note on the sign-off step providers skip covers the control that most affects the risk rows. Groups consolidating entities will also find the GCC payroll consolidation and parallel-run transition notes relevant.
“Payroll assurance” and “audit-ready” describe OPS’s operating discipline, controlled cycles, evidence packs, statutory checks and monthly governance within the agreed service scope. They are not a legal or tax guarantee and do not replace independent legal or tax advice.
Compliance check required: the UAE statutory positions above were verified against official and legal sources in September 2026, and this is guidance rather than legal advice. Statutory payroll requirements change regularly; confirm any specific obligation, figure or deadline with the relevant authority or professional adviser before acting on it. No contribution rate is stated here, because statutory contribution rates are the same cost under either operating model and are the figures most likely to have moved since publication.
Model your payroll cost of ownership with OPSIf your in-house payroll cost has never been priced against cover, regulatory reconfiguration and record retention, the comparison you are working from is probably missing the rows that matter. OPS will work through the register with you, entity by entity. You can also book a payroll consultation or visit www.ops.ae. |
Last Reviewed
September 2026, OPS Payroll & Compliance team. This guidance reflects OPS’s current understanding of applicable requirements and does not constitute legal advice. Statutory payroll requirements in the United Arab Emirates change regularly; confirm any specific obligation, figure or deadline with the relevant authority or professional adviser before acting on it.
Frequently Asked Questions
What does payroll outsourcing cost in the UAE?
Managed payroll is quoted per entity and per employee against a defined scope, so there is no single figure that applies across employers. The number that matters for a decision is not the invoice but the total cost of ownership on both sides: people, systems, statutory registrations, regulatory reconfiguration, record retention, cover and error correction. Ask any provider for inclusions, exclusions and chargeables in writing, and price the same register for your in-house function.
Is outsourced payroll cheaper than an in-house payroll team?
It depends on how many UAE entities you run and how much of the statutory load your in-house model is currently absorbing without pricing it. A single-entity employer with a stable rule set may find the two models close. An employer running several UAE entities, or one absorbing MOHRE, the Wage Protection System, GPSSA, Nafis, unemployment insurance and Federal Tax Authority duties without pricing them, is carrying more statutory load than the payroll salary suggests, and that is where the in-house cost per employee climbs.
What cost lines do in-house payroll budgets usually miss?
Three recur. Cover for the payroll role when the person is unavailable, which is a cost whether you buy it or not. Regulatory change, which behaves as a configuration project rather than a monthly task. And record retention priced to the longest applicable period rather than the shortest. A fourth, the finance and HR hours spent on inputs, variance review and approvals, is usually counted somewhere, just not in the payroll line.
What payroll compliance touchpoints does an employer maintain in the UAE?
In the UAE an employer works with MOHRE, the Wage Protection System, GPSSA where UAE or GCC nationals are employed, Nafis where Emiratisation thresholds apply, the employee unemployment insurance subscription, and Federal Tax Authority registration. These are maintained per legal entity, so a group with more than one UAE entity keeps the full set for each. Confirm the exact touchpoints per entity, since they depend on the workforce nationality mix and applicable thresholds.
How is end-of-service gratuity calculated in the UAE?
For eligible foreign full-time workers completing at least one year of continuous service, gratuity is calculated on last basic wage: 21 days’ basic wage for each of the first five years and 30 days’ basic wage for each subsequent year, with pro-rata entitlement for fractions of a year. The total must not exceed two years’ wage. The cap is expressed on total wage while the accrual runs on basic wage, which is the point most in-house formulas get wrong.
How long must payroll records be kept in the UAE?
Two separate duties run in parallel and neither displaces the other. The labour law requires worker records to be kept for not less than two years from the end of the worker’s service. Where payroll records form part of the records supporting a tax filing, Federal Tax Authority requirements apply to those records for at least seven years after the end of the tax period. Retention design should be set with tax and legal advisers, and against applicable data protection limits.
Sources
- Ministry of Human Resources and Emiratisation (MOHRE) on employer obligations, Emiratisation targets, and the wage-payment window under Ministerial Resolution No. 340 of 2026
- UAE Federal Decree-Law No. 33 of 2021 on the regulation of employment relations, for the wage obligation, the end-of-service formula, the basic wage definition and record retention, via the UAE Government portal (u.ae); Cabinet Resolution No. 1 of 2022, Article 16, for payment through the Wage Protection System
- General Pension and Social Security Authority (GPSSA) on Federal Decree-Law No. 57 of 2023, the 30-day registration duty and the Ma’ashi platform, and on registration of GCC nationals under the insurance protection extension system
- UAE Federal Tax Authority on the seven-year record retention requirement for records supporting a tax filing